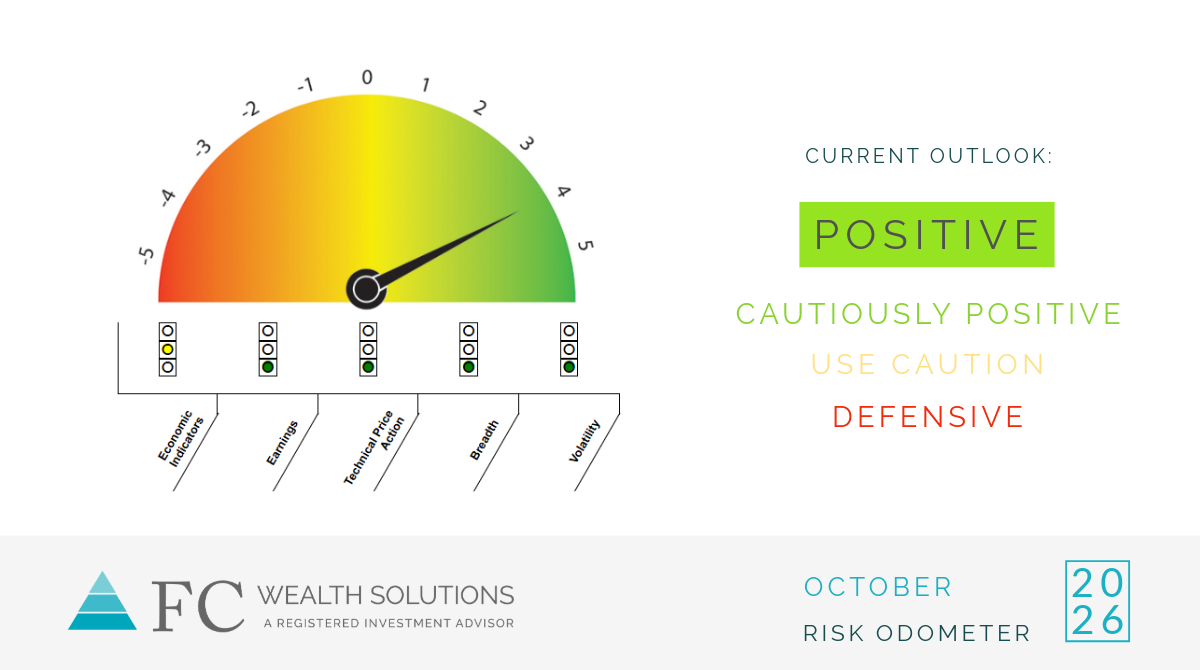
Our Risk Odometer held steady at +4 this month, marking the third consecutive month at this level. Our Current Outlook remains at its highest level of "Positive," a rating we have now maintained for over a year.
October brought no change to any of the five underlying indicators. Three straight months without movement is itself informative — it tells us the forces moving markets, even as they intensify, have not yet reached the threshold our model treats as a genuine inflection point.
The most recent headline event was the Federal Reserve's first rate hike in more than three years. The Fed raised the federal funds rate by 25 basis points in September, with Chair Kevin Warsh framing the move bluntly: inflation remains too high, for too long, and the committee was unwilling to wait any longer for it to come back in line. Updated Fed projections suggest at least one more hike could be on the table before year-end.
That hike arrived alongside a separate source of pressure: energy. Crude oil has pushed back above $90 a barrel on supply constraints tied to conflicts in the Middle East and Ukraine. Rising energy costs combined with the Fed's shift has driven the 10-year Treasury yield to its highest level since 2002. Higher-for-longer rates raise the bar for what stocks need to earn to justify current prices. Strong corporate earnings growth has largely absorbed that pressure rather than given way to it.
Investors also have another date circled on the calendar: November's midterm elections. Election years often bring a pickup in short-term volatility as markets digest the odds of a shift in the balance of power in Washington and what it could mean for fiscal and regulatory policy. History shows that volatility is typically temporary and rarely derails the market's underlying trend.
The markets are not absent risks despite the consistently positive outlook. Concentration in a handful of widely held companies, sticky inflation, a Fed willing to act, and multi-decade-high interest rates that raise the cost of capital across the economy are all themes on our radar screen.
Despite these risks, we remain very bullish. Bull markets always climb walls of worry, and the current environment is no exception. We continue to believe the underlying strength of the economy — fueled in large part by the insatiable demand for AI-related capital spending — is fundamentally sound. Should that spending or recent earnings growth fade, we would expect our Risk Odometer to reflect it and our opinions to change. Until then, we believe the markets will continue to climb the wall of worry bull markets so often do.
As always, we continue to believe our Risk Odometer provides guidance in making better investment decisions because it keeps us objective and disciplined. We use this methodology and advise our clients to do the same. Emotions are our enemies in investing.
It is important to understand that our Risk Odometer is not designed to anticipate small to medium corrections, typically those in the 5-15% range. Instead, it monitors for conditions which have typically preceded larger corrections. We believe trying to anticipate small to medium corrections sounds attractive but more often results in lost opportunity than savings.
The Equity Market Risk Odometer is our guide for judging risk in the equity market. It is used as a guide for investment decisions in our proprietary investment strategies. It is composed of various indicators based on leading economic indicators, earnings, technical price action, breadth, and volatility. Its score can range from +5 to -5. Readings greater than one are positive and readings less than or equal to zero are negative.